

Nearly a month ago, on April 9th, I warned that the orthodox economic models were blinding us to a catastrophic reality. As the mainstream financial press dusted off their 1970s playbooks and braced for hyper-inflationary price shocks following the closure of the Strait of Hormuz, I argued that we were instead facing a ‘brittle-fracture’.
I noted that the temporal lag of global shipping was masking an empty pipeline, and that the ‘final flush’ of Asian tankers arriving at our import terminals was a dying pulse, not a continuous supply. I predicted that when this biophysical disruption finally collided with the evaporating pool of global dollar liquidity, the result would not be 1970s inflation, but a deflationary collapse. “The market doesn’t inflate,” I wrote. “It breaks.”
Today, the temporal lag has run its course. The ships have stopped coming. And, precisely as the Socio-Economic Thermodynamic Entropy (SETE 2.0) framework predicted, we are watching the brittle-fracture unfold in real-time.
Despite roughly 12 million barrels per day remaining trapped behind a wall of asymmetric conflict, crude benchmarks are slipping. Retail petrol and diesel prices here in the UK and globally have actually begun a deflationary slide.
To the mainstream press, still trapped in the mechanistic worldview of the Strong Enlightenment tradition, this is evidence of ‘market resilience’. They point to shaky ceasefire talks in Islamabad, or a single US-flagged ship passing through the strait under heavy military escort, as proof that the market is rationally pricing in a return to normalcy.
This is a dangerous hallucination. We are not witnessing the magic of the market. We are witnessing the sound of the global organism entering metabolic failure.
The Inflection Point: Visualising the Fracture
If you look at the updated UK retail fuel price data overlaid against the US Dollar Index (DX-Y)—which I have appended below—the anatomy of this collapse is laid bare. The chart tracking pump price increases since the outbreak of the conflict on 28 February tells a story in two distinct acts.
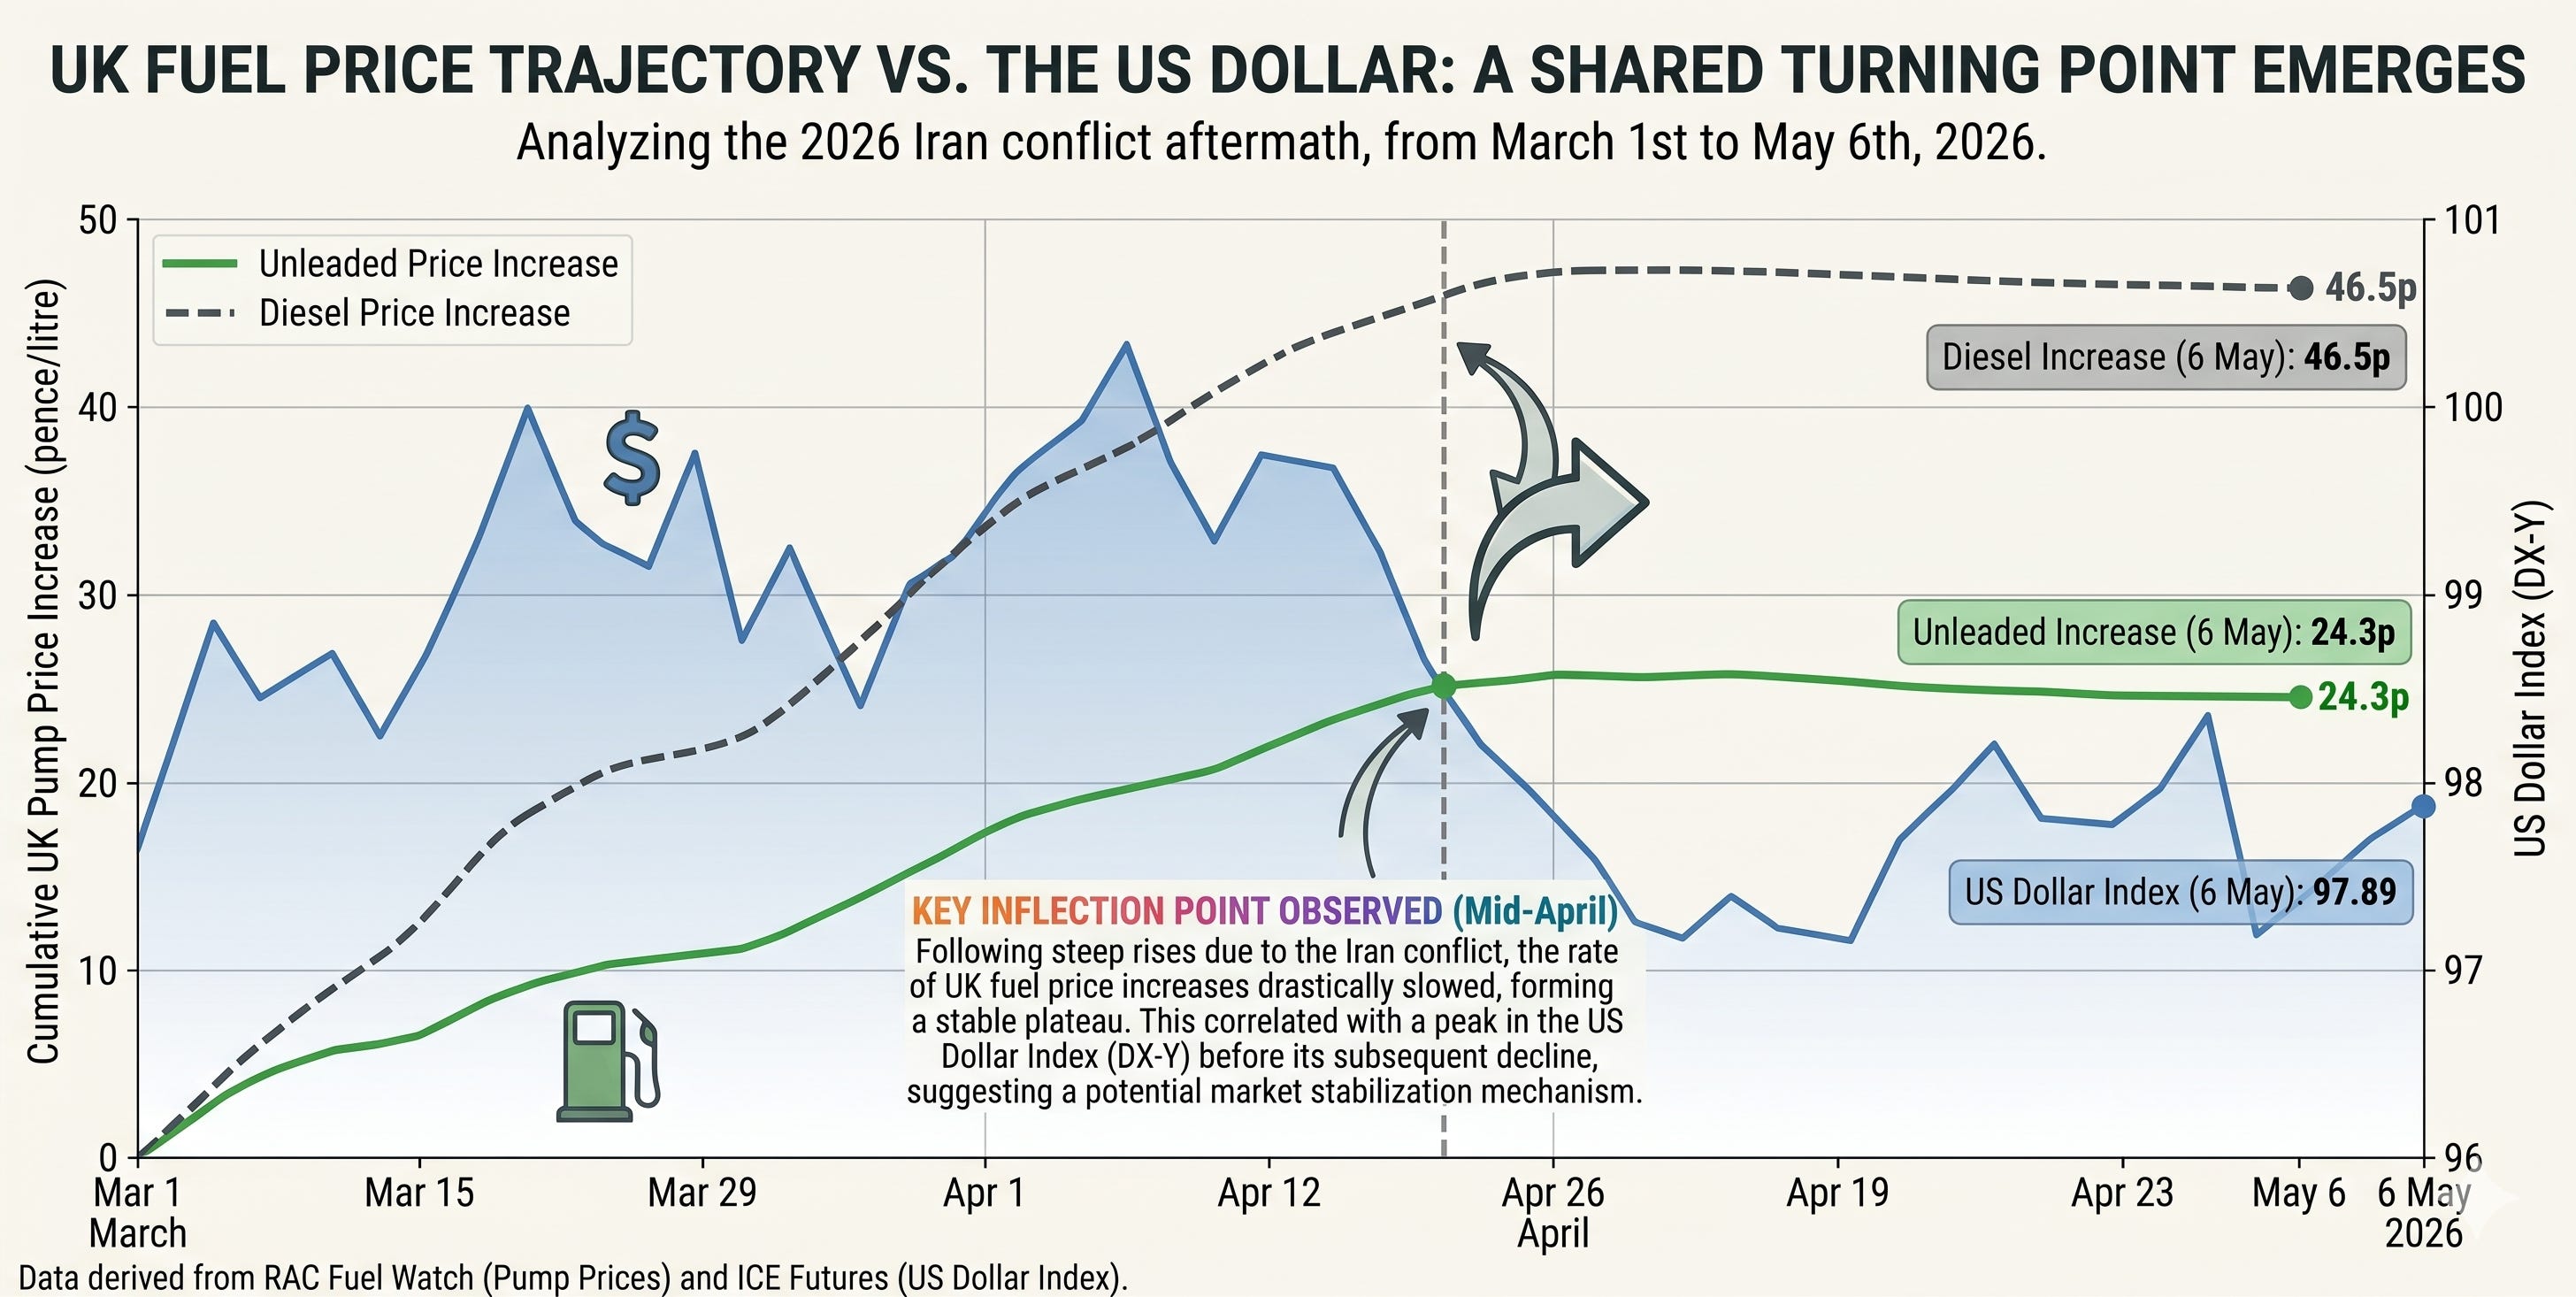
Throughout March, we see a steep, aggressive inflationary climb. Unleaded and diesel prices rocket upwards. This was the system’s predictable reaction: the market attempting to use leverage to bid up the marginal barrel to keep operations running. It was the final gasp of financialisation ɑf attempting to build a temporal bridge over a biophysical abyss.
But observe the critical sequence of events highlighted in the newly overlaid chart. The US Dollar Index steadily increases in strength—representing the global scramble for liquidity—until it violently flat-lines. Crucially, this flat-line occurs immediately prior to the inflection point in retail fuel prices.
The chart itself contains an annotation—a default to the mainstream interpretation—suggesting this correlation might represent a ‘potential market stabilisation mechanism’. It is profoundly revealing how even our standard analytical tools default to the mechanistic worldview of the Strong Enlightenment tradition. I did try to prevent this but it kept fighting back, so I’ve decided to leave it in place since.
Orthodox economists love the concept of ‘equilibrium’. To them, this DXY flat-line looks like a welcome stabilisation of forces, a return to balance. But this exposes the fatal flaw in mainstream macroeconomic modelling: they are attempting to map a static equilibrium onto what is fundamentally a non-equilibrium Complex Adaptive System (CAS).
A complex, dissipative thermodynamic system like the global economy never truly rests in equilibrium; it always has a trajectory. What the orthodox models misinterpret as a stable plateau is, thermodynamically, the visual signature of a structural liquidity vacuum. It is not a resting point; it is the violent phase-change of a system snapping onto a catabolic trajectory.
The Swap Line Paradox: The Transactional Void
It requires a radical re-evaluation of the data to understand what has actually happened here. The deflationary slide in fuel prices is far too steep to be a mere supply-side adjustment. What has occurred is that the UK—and the broader international periphery—has involuntarily stopped competing for the marginal barrel of fuel.
This is certainly not due to a political desire for domestic shortages. It is because the physical shortage has actually arrived.
During the initial phase of the crisis (March), the DXY spiked because allied central banks were desperately tapping emergency swap lines to secure the dollars needed to bid on skyrocketing oil. But observe the phase-change in mid-April. This inflection point represents the exact moment the temporal lag of shipping ran out. The final flush of phantom ships docked. The pipeline emptied.
Herein lies the paradox that breaks standard economic models: If there is a global dollar shortage, why would the DXY suddenly flat-line or weaken right before fuel prices collapse?
The answer is that you do not draw on a central bank swap line to bid for a barrel of oil that simply isn’t there.
The DXY is an index that measures the dollar against a basket of currencies; it requires trading volume to express strength. Because the physical oil is spatially inaccessible—trapped behind Hormuz or stranded in the wrong hemisphere—transactional volume has died. Since the UK and Europe cannot buy oil that does not physically exist, their demand for US dollars collapses. The massive upward buying pressure on the DXY vanishes instantly, pulling down nominal fuel prices in its wake.
The DXY flat-lines not because dollars are suddenly abundant, but because the global trade mechanism has suffered a cardiac arrest. The extremities haven’t just lost purchasing power; they have nothing left to purchase.
Metabolic Decoherence and Spatial Inaccessibility
This transactional void highlights a brutally physical dimension to our metabolic decoherence: spatial inaccessibility.
Standard economics treats the global oil market as a frictionless, theoretical pool where price seamlessly dictates allocation. But biophysical reality is bound by geography and transit topology. When the UK and other Western nations systematically dismantled their organic resilience (domestic refining capacity) to become a series of fragile import terminals, they wagered their survival on the flawless operation of Just-in-Time global shipping.
Today, even if the UK could conjure the dollar liquidity to bid for fuel, it wouldn’t matter. The fuel may exist theoretically on a global market spreadsheet, but it is spatially inaccessible. The ‘market’ cannot bridge a broken physical pipeline with financial leverage. The global organism is starving not just because its blood pressure has dropped, but because the arteries themselves have been severed.
The ‘Triffin Tax’ and Global Vasoconstriction
This physical seizure is vastly compounded by the financial centrifuge of US tariff policy.
Following the Supreme Court’s striking down of the IEEPA tariffs in February, the administration pivoted to Section 122 of the Trade Act of 1974, slamming a baseline 10% global surcharge on almost all imports. This 10% wall is not traditional protectionism; it is the Triffin Tax.
Historically, the Triffin Dilemma dictated that the US must run trade deficits to provide the world with the liquidity necessary to grow. But in our catabolic phase, the system has reversed. The US, possessing the highest institutional mass in human history, requires a staggering influx of exergy simply to prevent its own domestic infrastructure from collapsing.
By slapping this tariff on the world, the US is charging an exorbitant access fee just to clear whatever international trades remain. This acts as a massive vacuum, sucking eurodollars out of the international market and engineering a state of global vasoconstriction.
When a biological organism goes into shock from blood loss, it clamps down the blood vessels leading to the extremities to keep the heart and brain alive. The US is doing exactly this to the global economy. By sucking dollars inward, the US ensures that even if a trickle of fuel does become spatially accessible, the extremities are denied the liquidity needed to bid on it.
The Geopolitics of Catabolism: Washington vs. Tel Aviv
This macroeconomic reality forces us to address a common misconception regarding the ongoing conflict. Many geopolitical analysts look at the current stalemate in the Middle East—where Iran has successfully absorbed decapitation strikes and retains asymmetric control over the strait—and conclude that the US has blundered or ‘lost face’.
This fundamentally misreads American intentionality. The US went into this conflict knowing exactly what effect it would have on the essential flows through Hormuz. They did it anyway, gaming that the damage would be entirely fatal to their adversaries.
To understand this, we must separate the strategic objectives of Israel from those of the United States.
Israel’s objective is an anabolic (expansionary) project. Driven by an existential territorial imperative, they seek a ‘Greater Israel’—regional hegemony, the redrawing of borders, and the ability to dictate the regional routing table. This requires an astronomical expenditure of surplus exergy to maintain. Tel Aviv views the conflict mechanistically: eliminate the ‘bad components’, and the machine will run smoothly. This is why the current stalemate frustrates them; they require a definitive kinetic victory.
The United States, conversely, is managing a catabolic contraction. The US would be happy with Israeli hegemony, but it isn’t necessary. The American strategy is fundamentally dissipative. Their goal is the cheap denial of exergy to their peer competitors—namely, the highly leveraged, export-dependent manufacturing bases of Eurasia.
The US strategy is a biophysical siege. By combining the Triffin Tax with a physical chokepoint closure, Washington engineered a global dollar shortage at the exact moment of peak energy scarcity. They do not need a clean, kinetic victory in Iran. The stalemate provides the exact combination of global thermodynamic disruption and dollar-hegemony reinforcement needed to manage the resource entropy singularity on their own terms. They don’t need Iran to fall; they just need Eurasia to starve first.
Conclusion: The Catabolic Surplus
We are witnessing the snapping of the physical maintenance ratchet (Pmaint = kS). As a civilisation builds more intricate structures, the mandatory maintenance power required to prevent decay ratchets upward. The utility of the marginal barrel declines because an ever-increasing fraction of its energy is immediately cannibalised just to keep the lights on and the massive institutional debt serviced.
When the physical utility of that barrel drops below the energetic cost of acquiring it—a cost artificially inflated by the Triffin Tax, right as the physical supply vanishes—the pricing mechanism shatters.
We are now firmly in the salvage and triage phase. The ‘surplus’ keeping the core functioning today is no longer coming from growth; it is coming catabolically. The system has stopped maintaining its non-essential infrastructure. We are actively deleting fictitious wealth, debt, and global purchasing power to provide the exergy needed to keep the imperial core alive.
The slide in fuel prices that orthodox economists are celebrating is not a return to normalcy. It is the numbness that precedes ischemic necrosis. It is the real-time measurement of our global routing table violently erasing itself. The brittle-fracture has arrived.
This 'brittle fracture' is the physical signature of Systemic Cannibalism: when a system exhausts its abundance, it must consume its own foundations to survive. Sovereign debt and infrastructure decay are two sides of the same coin: we are liquidating our physical and human capital just to fund the illusion of growth. We’ve traded redundancy for efficiency, forgetting that in physics, redundancy is the only true source of resilience.
Oil never responds how economists predict because its the lifeblood and high prices simply cannot be supported. Demand destruction kicks in very quickly.